A roof insurance claim denial is not always the final word. A payment that falls short of the documented repair scope may also deserve a closer look. Homeowners and commercial property owners can ask their insurance company to review its decision and can provide additional information for consideration.
1. Get the Decision in Writing
Ask for the denial letter or the adjuster's complete estimate. Review the stated reason, deductible, depreciation, excluded damage, and any roof components that may have been left out. The insurance company must explain in writing why it denied all or part of the claim. A written decision gives you a clear starting point for your response.
2. Gather Your Claim Documents
Keep copies of your policy, photos, estimates, emails, receipts, and notes from every conversation. Check the policy for deadlines involving repairs, supplemental claims, appraisal, or legal action. Some deadlines can be shorter than expected, so respond promptly and ask a qualified professional for advice if you are unsure.
3. Have the Roof Inspected by Roof-Tech
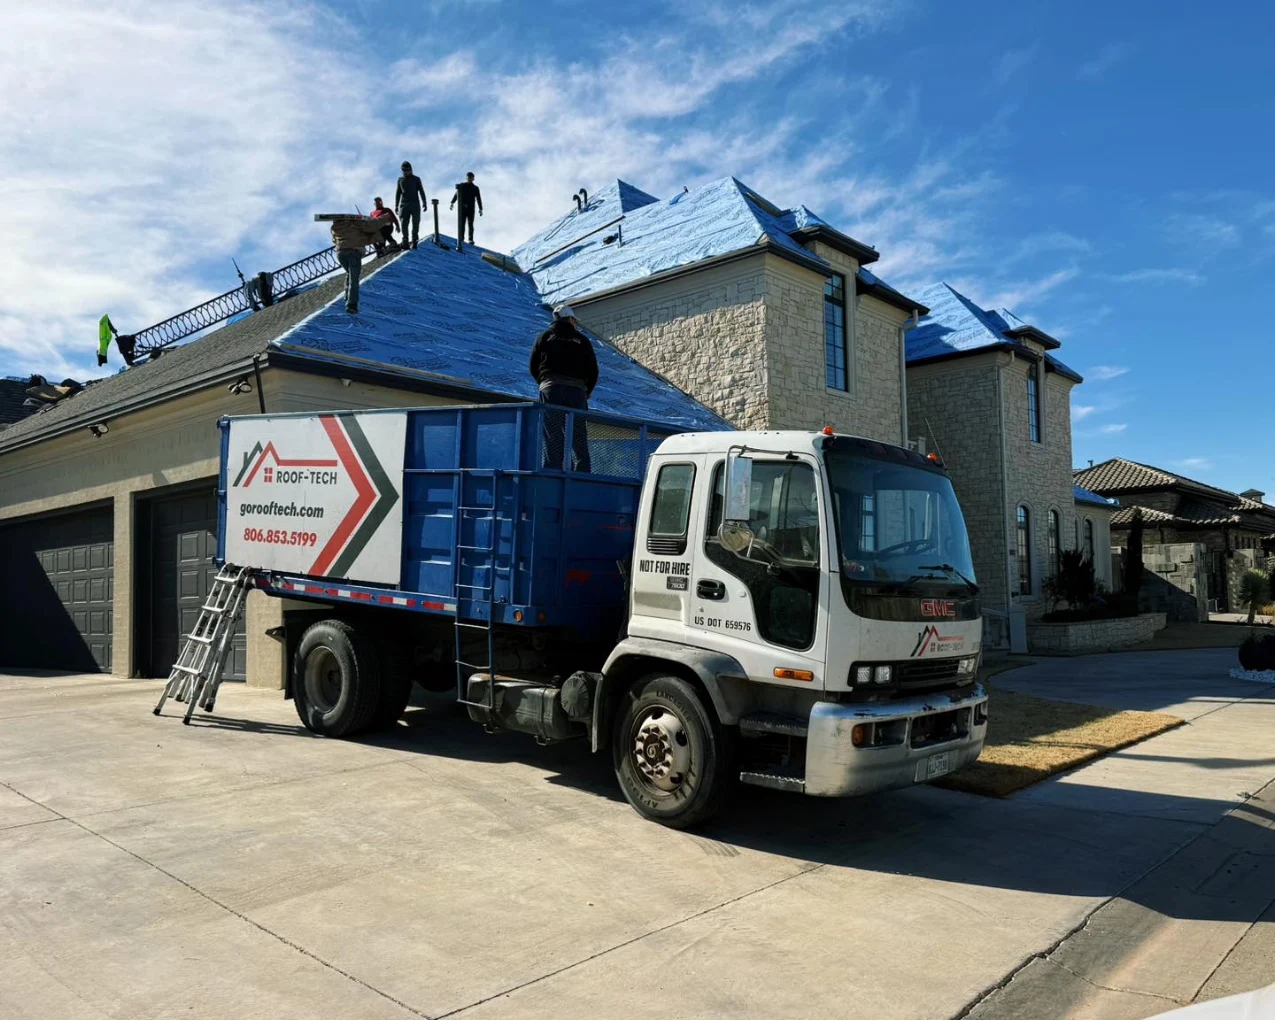
Roof damage is not always visible from the ground. An initial inspection can miss damaged decking, flashing, ventilation, or components that building code requires a contractor to replace. Roof-Tech can perform a professional roof inspection, document the condition of a residential or commercial roof, and prepare a detailed repair or replacement estimate.
We can identify where our roofing scope differs from the insurance estimate and document the technical reason for the difference. You can then provide that roofing information directly to your carrier.
4. Ask the Insurance Company to Reconsider
Send the insurer a written request for reconsideration or a supplemental review. Include supporting photos, measurements, estimates, and newly discovered damage. You can also request a reinspection and ask whether your roofing contractor may be present to point out documented roof conditions and explain the repair scope.
5. Know Your Other Options
If the disagreement continues, your policy may allow appraisal to determine the amount of a covered loss. Appraisal generally addresses the value of the damage, not whether the policy covers it. You may also file a complaint with the Texas Department of Insurance or speak with a licensed public adjuster or attorney.
A Note on Deductibles
Texas law requires the policyholder to pay the deductible, and an insurer can request proof of payment. A contractor offering to waive, absorb, or rebate your deductible is proposing something Texas law prohibits. The Texas Department of Insurance explains the deductible rules and how to recognize improper offers.
Start With a Professional Roof Inspection
Before accepting a denial or an estimate that will not cover the documented repair scope, contact Roof-Tech. Our West Texas team can inspect the property, identify and document roof damage, and provide a clear estimate based on the work the roof needs.
Free residential inspections are available. Commercial evaluations are scheduled by appointment.
Roof-Tech is a roofing contractor. We are not a public insurance adjuster or a law firm, and we do not act as a public insurance adjuster. We provide inspections, estimates, and technical roofing information. We do not interpret coverage or negotiate insurance settlements on a policyholder's behalf.


